Pre-release price: $2,497, 50% off, until Friday, December 18.
Reserve your copy today40 catalyst-driven stock ideas for the year ahead.
50% off until
Friday, December 18
Let's talk: schedule a call with a Boyar financial professional
Overview
The Forgotten Forty is Boyar Research’s flagship issue, published every December for more than three decades. It features the 40 companies in our research universe that we believe have the greatest potential to outperform in the year ahead, each chosen because of a catalyst we expect to unfold.
However, this is not just a list. Every company must already have been the subject of a full-length Boyar Research report, so each one-page snapshot is the result of deep research our team has already conducted.
40
Each includes our thesis, the catalysts we see and our estimate of what the company is worth.
Each idea draws on a full-length Boyar Research report. So while each snapshot is one page in length, thousands of hours of research go into this issue.
Every company has an identifiable catalyst that could unlock its value: a sale, a spin-off, an activist, a turnaround or other corporate actions we believe could unfold.
Many of the featured companies are not well followed by Wall Street analysts, which is oftentimes where we find the best ideas and add the most value to our subscribers.
Our research is completely independent, with no investment banking or trading business. Our sole mission is to identify profitable ideas for our clients.
1975
Since our founding, our sole focus has been identifying companies that trade at a discount to their intrinsic value.
Last year's complimentary report
123
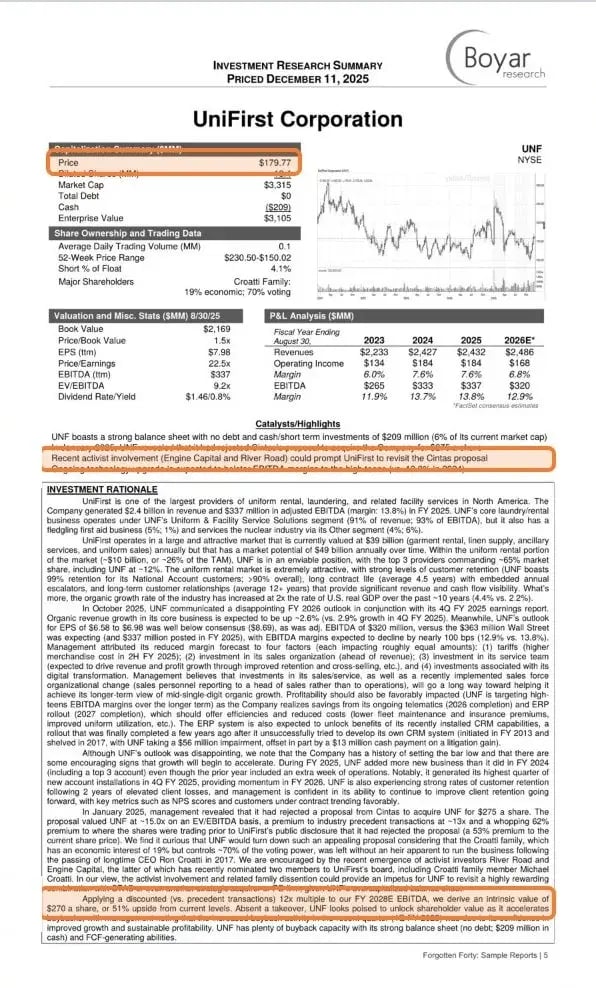
UniFirst report highlights
UniFirst traded at $179.77 when we priced the 2026 issue on December 11, 2025.
We identified that activist investors Engine Capital and River Road could pressure UniFirst to reconsider the Cintas proposal it had previously rejected.
We valued UniFirst at $270 a share, 51% above the price at the time of publication.
$179.77
Price at publication, December 11, 2025
$270
Our estimate of intrinsic value per share
~$310
Value of Cintas’s offer per share when announced, March 11, 2026
| Company | Catalyst we identified | Outcome in 2026 | Share price change since publication |
|---|---|---|---|
| Berkshire Hathaway (BRK.B) | Incoming CEO Greg Abel was likely to put Berkshire’s roughly $358 billion of cash and Treasury bills to work faster, through buybacks, acquisitions or stock purchases. |
Through September, Berkshire put a net $41.8 billion to work: $14.4 billion of buybacks, $16.2 billion of acquisitions and $11.2 billion of net stock purchases. It had been a net seller of stocks in each of the prior three years. |
+19.7% |
| Cooper Companies (COO) | Activist involvement had prompted a strategic review, including a possible sale of CooperSurgical. |
Not every catalyst materializes. The review concluded September 9 without a sale of CooperSurgical. We remain bullish on the company. |
−24.3% |
| Formula One Group (FWONA) | F1 was underearning in the U.S. A new five-year Apple deal (about $150 million a year, versus about $85 million from ESPN) would lift high-margin U.S. media revenue roughly 75% starting in 2026, and the split-off of Liberty Live would make FWONA a simpler, standalone stock. |
Liberty Live was split off on December 15, 2025. Apple’s U.S. broadcasts drew higher ratings than ESPN’s a year earlier, ahead of both Apple’s and F1’s expectations, and F1’s third-quarter revenue topped $1 billion for the first time. |
+22.3% |
| Madison Square Garden Sports (MSGS, now MSGK and MSGR) | The shares traded at a steep discount to the value of the Knicks and Rangers. We saw a spin-off of one of the teams, a sale of one or both of the teams or a minority stake sale as ways to unlock that value. |
In February 2026, MSG Sports announced it would explore separating the two teams. On October 26 it spun off the Rangers as MSG Rangers (MSGR) and renamed itself MSG Knickerbockers (MSGK), which owns the Knicks. |
+83.0%MSGK plus the MSGR shares received in the spin-off |
| SunOpta (STKL) | Fast growth in fruit snacks and protein shakes, with margin expansion expected to resume in the second half of 2026. |
Before our thesis could play out, Refresco agreed in February 2026 to acquire SunOpta for $6.50 a share in cash. The deal closed May 1. |
+68.8% |
Prices are as of December 11, 2025, when the 2026 issue was priced. In the table, share price changes run from December 11, 2025, to November 12, 2026, and exclude dividends. These are changes in share prices, not returns of any account. Past performance is not indicative of future results. See disclosures below.
What others are saying
It's been 15 years since I received my first edition of the Forgotten Forty, and I've never been disappointed… There is no doubt, Boyar has added 'alpha' to my clients' total return over the years.
I'm a long time and happy subscriber to Boyar's Forgotten Forty. I used the service for years while running institutional portfolios and have continued to use the service running my family office.
Boyar's Forgotten Forty is an excellent filter for stock pickers as they narrow their hunt.
In the news
Jonathan Boyar, president of Boyar Research, has discussed the Forgotten Forty on CNBC, Fox Business and Yahoo Finance, and in Barron's.
Fox Business · December 2025
Yahoo Finance · January 2026
Barron's
Pre-release offer
Reserve now and, as a bonus, receive our most recent research issue immediately.
50% off until Friday, December 18, at 11:59 p.m. ET
40 one-page reports, each with our thesis, catalysts and estimate of intrinsic value
Delivered in December, with every idea backed by a full-length Boyar Research report
As a bonus, our most recent research issue, containing four in-depth reports
Receive two complimentary reports from last year’s issue, exactly as we published them.
Questions? Call a Boyar financial professional at (212) 995-8300
Questions
In December. If you reserve a copy now, you receive it as soon as it is published.
As a bonus, our most recent research issue, containing four in-depth reports on companies we believe are undervalued.
Each company must already have been the subject of a full-length Boyar Research report and have an identifiable catalyst that we believe could unlock its value.
Our investment thesis, the catalysts we see, our estimate of intrinsic value and the price at publication, all on a single page.
Yes. Request two complimentary reports from last year’s issue, exactly as we published them.
Boyar Research was founded by Mark Boyar in 1975. Our team of six investment professionals has more than 150 years of combined experience, and our research is completely independent, with no investment banking or trading business.